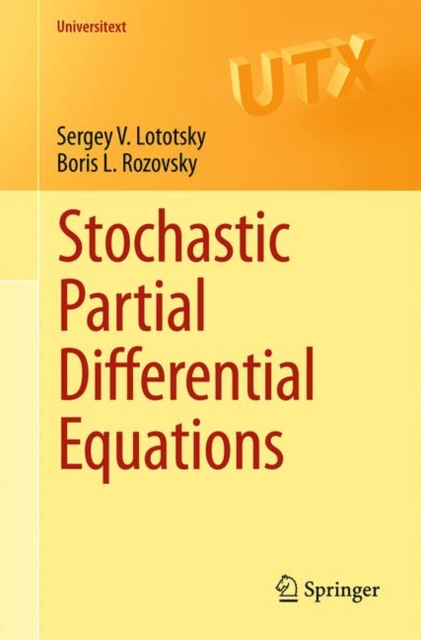
Taking readers with a basic knowledge of probability and real analysis to the frontiers of a very active research discipline, this textbook provides all the necessary background from functional analysis and the theory of PDEs.
This book promotes and describes the application of objective and effective decision making in asset management based on mathematical models and practical techniques that can be easily implemented in organizations.
This contributed volume provides readers with an overview of the most recent developments in the mathematical fields related to fractals, including both original research contributions, as well as surveys from many of the leading experts on modern fractal theory and applications.
This book proposes the formulation of an efficient methodology that estimates energy system uncertainty and predicts Remaining Useful Life (RUL) accurately with significantly reduced RUL prediction uncertainty.
This volume of selected and peer-reviewed contributions on the latest developments in time series analysis and forecasting updates the reader on topics such as analysis of irregularly sampled time series, multi-scale analysis of univariate and multivariate time series, linear and non-linear time series models, advanced time series forecasting methods, applications in time series analysis and forecasting, advanced methods and online learning in time series and high-dimensional and complex/big data time series.
The YUIMA package is the first comprehensive R framework based on S4 classes and methods which allows for the simulation of stochastic differential equations driven by Wiener process, Levy processes or fractional Brownian motion, as well as CARMA, COGARCH, and Point processes.
The concepts and techniques presented in this volume originated from the fields of dynamics, statistics, control theory, computer science and informatics, and are applied to novel and innovative real-world applications.
This book presents the fundamental notions and advanced mathematical tools in the stochastic modeling of uncertainties and their quantification for large-scale computational models in sciences and engineering.
Providing an introduction to stochastic optimal control in infinite dimension, this book gives a complete account of the theory of second-order HJB equations in infinite-dimensional Hilbert spaces, focusing on its applicability to associated stochastic optimal control problems.
This updated and revised first-course textbook in applied probability provides a contemporary and lively post-calculus introduction to the subject of probability.
This textbook takes a strategic approach to the broad-reaching subject of experimental design by identifying the objectives behind an experiment and teaching practical considerations that govern design and implementation, concepts that serve as the basis for the analytical techniques covered.
This 2nd edition textbook offers a rigorous introduction to measure theoretic probability with particular attention to topics of interest to mathematical statisticians-a textbook for courses in probability for students in mathematical statistics.
Studying the fine properties of solutions to Stochastic (Partial) Differential Equations with reflection at a boundary, this book begins with a discussion of classical one-dimensional diffusions as the reflecting Brownian motion, devoting a chapter to Bessel processes, and moves on to function-valued solutions to SPDEs.
This book is divided into two parts, the first of which seeks to connect the phase transitions of various disciplines, including game theory, and to explore the synergies between statistical physics and combinatorics.
This book, dedicated to Winfried Stute on the occasion of his 70th birthday, presents a unique collection of contributions by leading experts in statistics, stochastic processes, mathematical finance and insurance.
This monograph aims to promote original mathematical methods to determine the invariant measure of two-dimensional random walks in domains with boundaries.
This textbook provides an exciting new addition to the area of network science featuring a stronger and more methodical link of models to their mathematical origin and explains how these relate to each other with special focus on epidemic spread on networks.
Analyzing the phase transition from diffusive to localized behavior in a model of directed polymers in a random environment, this volume places particular emphasis on the localization phenomenon.
This is the only book discussing multifractal properties of densities of stable superprocesses, containing latest achievements while also giving the reader a comprehensive picture of the state of the art in this area.
This book comprises nine selected works on numerical and computational methods for solving multiobjective optimization, game theory, and machine learning problems.
This book offers an introduction to the theory of non-autonomous and stochastic dynamical systems, with a focus on the importance of the theory in the Applied Sciences.
The present volume develops the theory of integration in Banach spaces, martingales and UMD spaces, and culminates in a treatment of the Hilbert transform, Littlewood-Paley theory and the vector-valued Mihlin multiplier theorem.
This text develops the necessary background in probability theory underlying diverse treatments of stochastic processes and their wide-ranging applications.
This book focuses on the application and development of information geometric methods in the analysis, classification and retrieval of images and signals.
This volume consists of papers inspired by the special session on pseudo-differential operators at the 10th ISAAC Congress held at the University of Macau, August 3-8, 2015 and the mini-symposium on pseudo-differential operators in industries and technologies at the 8th ICIAM held at the National Convention Center in Beijing, August 10-14, 2015.
Focusing on p-adic and adelic analogues of pseudodifferential equations, this monograph presents a very general theory of parabolic-type equations and their Markov processes motivated by their connection with models of complex hierarchic systems.
This Festschrift resulted from a workshop on "e;Advanced Modelling in Mathematical Finance"e; held in honour of Ernst Eberlein's 70th birthday, from 20 to 22 May 2015 in Kiel, Germany.
This research monograph brings together, for the first time, the varied literature on Yosida approximations of stochastic differential equations (SDEs) in infinite dimensions and their applications into a single cohesive work.
Building upon the previous editions, this textbook is a first course in stochastic processes taken by undergraduate and graduate students (MS and PhD students from math, statistics, economics, computer science, engineering, and finance departments) who have had a course in probability theory.