This new edition of Stochastic Linear Programming: Models, Theory and Computation has been brought completely up to date, either dealing with or at least referring to new material on models and methods, including DEA with stochastic outputs modeled via constraints on special risk functions (generalizing chance constraints, ICC's and CVaR constraints), material on Sharpe-ratio, and Asset Liability Management models involving CVaR in a multi-stage setup.
Although studies on multiobjective mathematical programming under uncertainty have been accumulated and several books on multiobjective mathematical programming under uncertainty have been published (e.
Applied Probability presents a unique blend of theory and applications, with special emphasis on mathematical modeling, computational techniques, and examples from the biological sciences.
Research in Bayesian analysis and statistical decision theory is rapidly expanding and diversifying, making it increasingly more difficult for any single researcher to stay up to date on all current research frontiers.
This handbook aims to highlight fundamental, methodological and computational aspects of networks of queues to provide insights and to unify results that can be applied in a more general manner.
In 1945, very early in the history of the development of a rigorous analytical theory of probability, Feller (1945) wrote a paper called "e;The fundamental limit theorems in probability"e; in which he set out what he considered to be "e;the two most important limit theorems in the modern theory of probability: the central limit theorem and the recently discovered .
"e;Decision Systems and Non-stochastic Randomness"e; is the first systematic presentation and mathematical formalization (including existence theorems) of the statistical regularities of non-stochastic randomness.
Stochastic processes and diffusion theory are the mathematical underpinnings of many scientific disciplines, including statistical physics, physical chemistry, molecular biophysics, communications theory and many more.
This book is the third revised and updated English edition of the German textbook \Versuchsplanung und Modellwahl"e; by Helge Toutenburg which was based on more than 15 years experience of lectures on the course \- sign of Experiments"e; at the University of Munich and interactions with the statisticians from industries and other areas of applied sciences and en- neering.
This is a collection of essays based on lectures that author has given on various occasions on foundation of quantum theory, symmetries and representation theory, and the quantum theory of the superworld created by physicists.
In this monograph the authors develop a theory for the robust control of discrete-time stochastic systems, subjected to both independent random perturbations and to Markov chains.
This volume covers recent developments in the design, operation, and management of telecommunication and computer network systems in performance engineering and addresses issues of uncertainty, robustness, and risk.
The purpose of this book is to provide the reader with a solid background and understanding of the basic results and methods in probability theory before entering into more advanced courses (in probability and/or statistics).
Engineers are expected to design structures and machines that can operate in challenging and volatile environments, while allowing for variation in materials and noise in measurements and signals.
An Introduction to Stochastic Processes with Applications to Biology, Second Edition presents the basic theory of stochastic processes necessary in understanding and applying stochastic methods to biological problems in areas such as population growth and extinction, drug kinetics, two-species competition and predation, the spread of epidemics, and
Filling the void between surveys of the field with relatively light mathematical content and books with a rigorous, formal approach to stochastic integration and probabilistic ideas, Stochastic Financial Models provides a sound introduction to mathematical finance.
A First Course in Probability with an Emphasis on Stochastic ModelingProbability and Stochastic Modeling not only covers all the topics found in a traditional introductory probability course, but also emphasizes stochastic modeling, including Markov chains, birth-death processes, and reliability models.
While many financial engineering books are available, the statistical aspects behind the implementation of stochastic models used in the field are often overlooked or restricted to a few well-known cases.
The seventh volume in the SemStat series, Statistical Methods for Stochastic Differential Equations presents current research trends and recent developments in statistical methods for stochastic differential equations.
Since the emerging discipline of engineering enterprise systems extends traditional systems engineering to develop webs of systems and systems-of-systems, the engineering management and management science communities need new approaches for analyzing and managing risk in engineering enterprise systems.
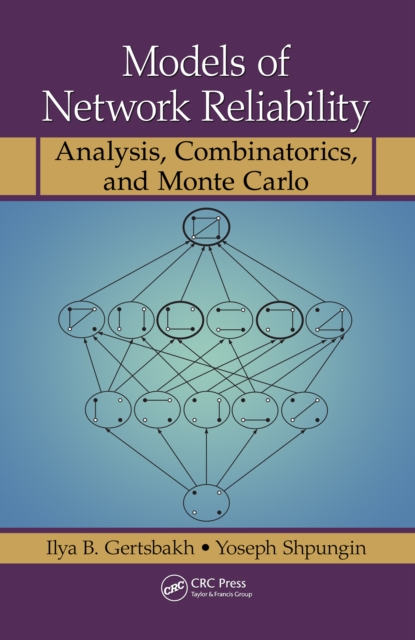
Unique in its approach, Models of Network Reliability: Analysis, Combinatorics, and Monte Carlo provides a brief introduction to Monte Carlo methods along with a concise exposition of reliability theory ideas.
Analysis of queues is used in a variety of domains including call centers, web servers, internet routers, manufacturing and production, telecommunications, transportation, hospitals and clinics, restaurants, and theme parks.
In an easy-to-understand, nontechnical yet mathematically elegant manner, An Introduction to Exotic Option Pricing shows how to price exotic options, including complex ones, without performing complicated integrations or formally solving partial differential equations (PDEs).